

If you borrowed money from NetCredit in Georgia, you may have paid interest rates that violate state law. The netcredit lawsuit georgia situation has grown significantly heading into 2026, with more borrowers questioning whether their loans were ever legal in the first place.
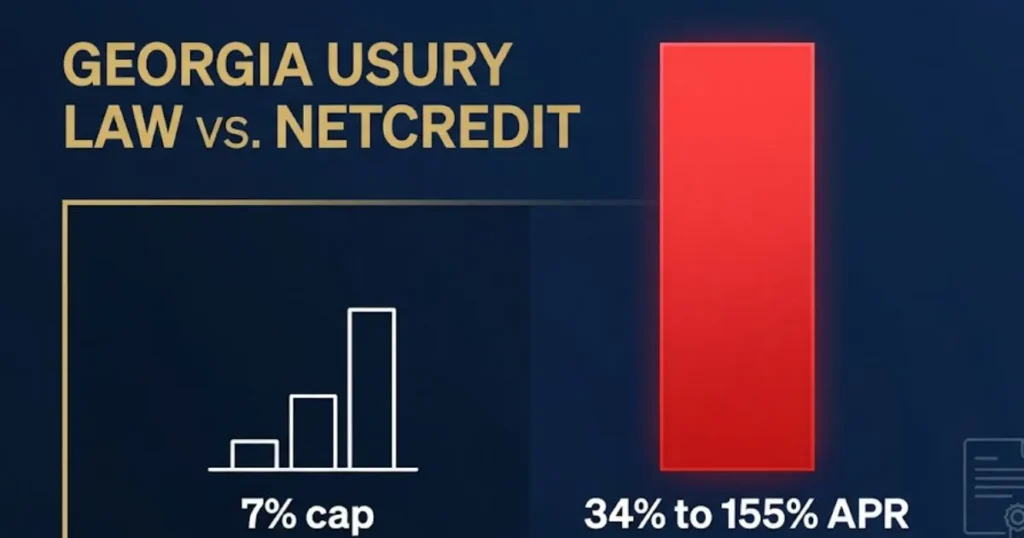
Georgia caps most consumer loan interest at 5% per annum under O.C.G.A. 7-4-2, with contract rates allowed up to 7%. NetCredit has charged APRs ranging from 34% to over 150%. That gap is staggering.
This article covers every angle of the legal battle between Georgia borrowers and NetCredit. You will learn about class action status, settlement possibilities, how Georgia’s usury laws apply, the tribal lending model NetCredit uses, and exactly how to fight back.
Some Georgia borrowers have paid back two to three times their original loan amount in interest alone. That kind of math does not add up, and courts are starting to agree.
NetCredit Lawsuit Georgia: What You Need to Know in 2026
The netcredit lawsuit georgia situation in 2026 centers on whether NetCredit’s high-interest loans violate Georgia’s strict usury statutes. Georgia borrowers have filed individual lawsuits and regulatory complaints arguing that NetCredit operates as an unlicensed lender charging illegal rates.
NetCredit is an online lending platform owned by Enova International, a publicly traded company based in Chicago. It offers unsecured personal loans and lines of credit to consumers with lower credit scores. In Georgia, these loans have carried APRs that far exceed what state law permits.
The core legal argument is straightforward. Georgia law sets interest rate limits. NetCredit charges rates above those limits. The question is whether NetCredit can legally do that through its lending partnerships and corporate structure.
Several Georgia borrowers have reported paying back $7,000 to $10,000 on loans of $3,000 to $5,000. These numbers have fueled complaints to state and federal regulators throughout 2024 and 2025, building momentum heading into 2026.
| Detail | Info |
|---|---|
| Company | NetCredit (Enova International) |
| Loan Types | Personal loans, lines of credit |
| Georgia APR Range | 34% to 155% reported |
| Georgia Legal Rate Cap | 5% (general), 7% (by contract) |
| Key Georgia Statute | O.C.G.A. 7-4-2 |
| Regulatory Bodies Involved | CFPB, Georgia Dept. of Banking |
The legal pressure on NetCredit in Georgia has been building for years. 2026 could be the year it reaches a tipping point.
NetCredit Class Action Lawsuit 2026 Updates
As of 2026, there is no single certified class action against NetCredit specific to Georgia borrowers. However, multiple individual lawsuits and state-level regulatory actions are active, and class certification efforts are underway in several jurisdictions that include Georgia plaintiffs.
The challenge with class certification is NetCredit’s mandatory arbitration clause. Nearly every NetCredit loan agreement includes a provision requiring disputes to go through binding arbitration, not court. This clause also typically includes a class action waiver.
Some attorneys have argued that these arbitration clauses are unconscionable under Georgia law when attached to loans that already violate state usury statutes. If a loan is void because it breaks Georgia law, the argument goes, then every clause in that loan agreement is void too.
- Multiple individual arbitration claims have been filed by Georgia borrowers since 2024
- Attorney groups are coordinating “mass arbitration” strategies against NetCredit
- The CFPB has taken separate enforcement interest in Enova International’s lending practices
- Several states beyond Georgia have opened investigations into NetCredit’s rate structures
Key fact: Mass arbitration, where hundreds of individual claims are filed simultaneously, can cost a company like NetCredit millions in filing fees alone. That financial pressure often pushes companies toward settlement discussions faster than a single class action would.
Watch for developments in the second half of 2026. The legal pipeline is active.
Is NetCredit Legal in Georgia?
NetCredit operates in Georgia, but the legality of its lending practices is actively disputed. Georgia’s usury statutes set some of the strictest interest rate caps in the country, and NetCredit’s rates appear to exceed those caps by a wide margin.
Under O.C.G.A. 7-4-2, the legal interest rate in Georgia is 7% per year on loans where parties agree to a rate in writing. Without a written agreement, the rate drops to 5%. Criminal usury under O.C.G.A. 7-4-18 kicks in at rates above 5% per month, which equals 60% annually.
NetCredit has offered Georgia borrowers APRs of 34% to over 150%, depending on the loan product and borrower profile. Even at the lower end of that range, those rates exceed Georgia’s civil usury cap.
So how does NetCredit continue to operate? The company uses a bank partnership model. Loans are originated through a federally chartered or state-chartered bank, such as Republic Bank & Trust in Kentucky. Because the bank is chartered in a state with higher rate limits, NetCredit argues the bank’s home-state rates apply, not Georgia’s.
| Legal Question | Status in Georgia |
|---|---|
| Does Georgia cap interest rates? | Yes, 7% by contract, 5% default |
| Does NetCredit exceed those caps? | Yes, rates range from 34% to 155% |
| Is bank partnership a legal shield? | Disputed; “true lender” challenges exist |
| Has Georgia AG taken action? | Investigations reported, no public suit yet |
| Are NetCredit loans enforceable in GA? | Actively challenged in 2026 |
Think of it like this: if you rent your friend’s driver’s license to buy alcohol because you are underage, that does not make the purchase legal. Critics say NetCredit’s bank partnership works the same way.
Key Takeaway: NetCredit operates in Georgia through a bank partnership model, but Georgia borrowers have strong legal arguments that these high-interest loans violate state usury law and may be unenforceable.
NetCredit Predatory Lending in Georgia
NetCredit’s lending practices in Georgia meet many of the standard definitions of predatory lending. Predatory lending involves loan terms designed to strip wealth from borrowers rather than help them build financial stability.
Here are the hallmarks of predatory lending and how NetCredit’s Georgia loans measure up:
- Excessive interest rates: NetCredit APRs in Georgia often exceed 100%. A $5,000 loan at 150% APR costs the borrower $7,500 in interest in just one year
- Targeting vulnerable borrowers: NetCredit markets to consumers with credit scores between 520 and 700, people who often have limited alternatives
- Repeat borrowing cycles: Many Georgia borrowers report taking new NetCredit loans to pay off existing ones, creating a debt spiral
- Lack of ability-to-repay analysis: Complaints indicate that NetCredit approves loans without adequately verifying whether the borrower can afford the payments
- Hidden fee structures: Origination fees and finance charges are often buried in loan documents
Georgia’s Fair Lending Act and the federal Truth in Lending Act (TILA) both address predatory lending practices. Under TILA, lenders must clearly disclose the APR, total finance charges, and payment schedule before the borrower signs.
Some Georgia borrowers have reported that they did not fully understand the total cost of their NetCredit loans until they had already made several payments. By that point, a significant portion of each payment had gone toward interest rather than principal.
The math tells the story. A $3,500 NetCredit loan at 99% APR over 42 months results in total payments of approximately $8,900. The borrower pays back more than 2.5 times the original loan amount.
NetCredit Settlement Georgia: What to Expect
No public settlement has been announced between NetCredit and Georgia borrowers as of early 2026. However, settlement discussions are likely happening behind closed doors, especially given the growing number of individual claims and regulatory pressure.
When high-interest lenders face this kind of legal heat, settlements typically follow a pattern. The company agrees to forgive a portion of outstanding debt, refund some interest payments, and change its lending practices in the state going forward.
Based on settlements in similar predatory lending cases, Georgia borrowers could potentially see:
| Settlement Type | Estimated Range |
|---|---|
| Interest refund per borrower | $500 to $3,000 |
| Outstanding loan forgiveness | 25% to 100% of balance |
| Fee refunds | $50 to $500 |
| Regulatory fine (state level) | $1 million to $10 million |
These are estimates based on comparable cases. The CFPB’s 2024 actions against similar lenders resulted in refunds averaging $1,200 per affected borrower. Georgia borrowers who paid the highest APRs would likely receive the largest refunds.
Settlement timing depends on several factors. If the CFPB takes formal enforcement action against NetCredit or Enova International in 2026, that could accelerate negotiations. State-level action from the Georgia Attorney General’s office would have a similar effect.
Keep all your NetCredit loan documents, payment records, and correspondence. These records will matter when the time comes.
NetCredit Georgia Interest Rate Breakdown
NetCredit charges Georgia borrowers interest rates that dwarf what most people consider normal. Understanding exactly what you are paying helps you see why these loans are at the center of legal challenges.
Here is how NetCredit’s Georgia rates compare to other lending options:
| Loan Type | Typical APR | $5,000 Loan Total Cost (3 years) |
|---|---|---|
| NetCredit (Georgia) | 34% to 155% | $9,500 to $22,000+ |
| Credit Union Personal Loan | 6% to 18% | $5,900 to $6,500 |
| Bank Personal Loan | 8% to 15% | $6,200 to $6,300 |
| Credit Card Cash Advance | 20% to 30% | $6,600 to $7,500 |
| Georgia Legal Max (contract) | 7% | $5,550 |
That table is a gut punch. A Georgia borrower who takes a $5,000 loan from NetCredit at 99% APR could end up paying over $14,000 by the time it is paid off. The same loan from a credit union might cost $6,200 total.
The interest rate is not just a number. It determines whether a loan helps you or traps you. At 99% APR, roughly half of every monthly payment goes straight to interest during the first year. Your principal barely moves.
NetCredit justifies these rates by pointing to the higher risk profile of its borrowers. But Georgia’s legislature decided long ago that no consumer should pay more than 7% annual interest on a loan, regardless of credit risk. That is the law.
Key Takeaway: NetCredit’s Georgia interest rates can be 5 to 20 times higher than the state’s legal cap, and borrowers often pay back double or triple their original loan amount over the life of the loan.
What Is the NetCredit APR in Georgia?
The NetCredit APR in Georgia ranges from approximately 34% to 155%, depending on the borrower’s credit profile, loan amount, and repayment term. These rates are among the highest in the online lending industry.
APR stands for Annual Percentage Rate. It includes not just the interest rate but all finance charges, origination fees, and other costs expressed as a yearly percentage. The APR gives you the true cost of borrowing.
For Georgia borrowers, here is what different NetCredit APR levels actually cost on a $4,000 loan repaid over 36 months:
| APR | Monthly Payment | Total Paid | Total Interest Paid |
|---|---|---|---|
| 34% | $173 | $6,228 | $2,228 |
| 75% | $270 | $9,720 | $5,720 |
| 99% | $340 | $12,240 | $8,240 |
| 155% | $530 | $19,080 | $15,080 |
At 155% APR, you pay back nearly five times what you borrowed. That is not a loan in any meaningful sense. It is a wealth extraction tool.
The federal Truth in Lending Act requires NetCredit to disclose the APR before you sign. But many borrowers report that the APR disclosure gets lost in a stack of digital paperwork. By the time you realize what you have agreed to, the payments are already rolling.
Compare this to what Georgia law allows. Even the criminal usury threshold of 60% APR is lower than many NetCredit rates. That means some NetCredit loans may not just be civilly unenforceable in Georgia. They may be criminally usurious.
Georgia Usury Law and How It Applies to NetCredit
Georgia’s usury statutes are some of the oldest and strictest in the nation, and they apply directly to the kind of high-interest loans NetCredit offers. Under these laws, loans charging excessive interest can be declared void and unenforceable.
The key statutes are:
- O.C.G.A. 7-4-2: Sets the maximum contract interest rate at 7% per year for most consumer loans. Without a written rate agreement, the default rate is 5%
- O.C.G.A. 7-4-18: Makes it a criminal offense to charge interest exceeding 5% per month (60% per year) on loans under $3,000
- O.C.G.A. 7-4-10: Provides that usurious contracts are void and the borrower may recover double the interest paid
That last statute is the big one for NetCredit borrowers. If a court finds that your NetCredit loan is usurious under Georgia law, you might not owe anything on it. You could also recover twice the interest you already paid.
| Georgia Usury Provision | What It Means for NetCredit Borrowers |
|---|---|
| 7% annual cap (civil) | Most NetCredit rates exceed this by 5x to 20x |
| 60% annual cap (criminal) | Many NetCredit loans exceed even this threshold |
| Void contract remedy | Loan may be unenforceable; no obligation to repay |
| Double interest recovery | Borrower can sue for 2x interest already paid |
Here is the real world impact. If you took a $3,000 NetCredit loan and paid $4,500 in interest, a Georgia court could void the remaining balance and order NetCredit to pay you $9,000 (double the interest paid).
Georgia did not set these limits arbitrarily. Usury laws exist to prevent exactly what NetCredit does: charging desperate borrowers rates that make it nearly impossible to pay off the principal.
The NetCredit Tribal Lending Loophole Explained
NetCredit does not directly use the tribal lending model, but its parent company Enova International operates in a regulatory gray area that functions similarly. Understanding this structure is key to understanding why NetCredit believes it can charge the rates it does in Georgia.
The tribal lending model works like this: a lender partners with a Native American tribal entity, which claims sovereign immunity from state lending laws. Because tribal nations operate as sovereign governments, they argue state interest rate caps do not apply to them.
NetCredit takes a slightly different approach called the bank partnership model or “rent-a-bank” arrangement. Instead of a tribal entity, NetCredit partners with Republic Bank & Trust, a Kentucky-chartered bank. Since federal law allows banks to export their home state’s interest rates to borrowers in other states, NetCredit claims Kentucky’s more permissive rate structure applies, not Georgia’s.
Both models work toward the same goal: avoiding strict state lending laws.
- Tribal model: Claims sovereign immunity to dodge state usury caps
- Bank model: Claims rate exportation rights under federal banking law
- Result in both cases: Borrowers in states like Georgia get hit with rates that state law would otherwise prohibit
Georgia regulators and courts have started pushing back on both models. The “true lender” doctrine asks a simple question: who is the real lender here? If NetCredit is the one funding, marketing, and servicing the loan, then NetCredit is the true lender, not Republic Bank. And if NetCredit is the true lender, Georgia’s rate caps apply.
The FDIC finalized its true lender rule guidance, and the CFPB has signaled interest in examining these arrangements more closely in 2025 and 2026. For Georgia borrowers, these regulatory shifts could be the key that unlocks real legal relief.
Key Takeaway: NetCredit uses a bank partnership structure to circumvent Georgia’s interest rate caps, but the “true lender” doctrine could strip away that legal shield in 2026.
How to Sue NetCredit in Georgia
Georgia borrowers can sue NetCredit individually in state court, file claims in small claims court, or pursue arbitration. The path you choose depends on your loan amount, the arbitration clause in your agreement, and your goals.
Here is a step-by-step breakdown:
Step 1: Gather your documents
Collect your loan agreement, payment history, bank statements showing payments to NetCredit, and any emails or letters from the company. Calculate the total interest and fees you paid versus your original loan amount.
Step 2: Calculate your potential damages
Under O.C.G.A. 7-4-10, you may be entitled to:
- Voiding of the loan (no further obligation to pay)
- Recovery of double the interest you already paid
- Court costs and attorney fees in some cases
Step 3: Decide your venue
| Option | Best For | Loan Amount | Cost to File |
|---|---|---|---|
| Georgia Small Claims Court | Individuals with smaller loans | Up to $15,000 | $45 to $75 |
| Georgia Superior Court | Larger claims or complex cases | Over $15,000 | $200+ |
| Arbitration (AAA or JAMS) | If forced by loan agreement | Any amount | Varies (often $200) |
| Mass Arbitration | Coordinated individual claims | Any amount | Often subsidized by attorneys |
Step 4: Address the arbitration clause
If your loan agreement requires arbitration, you have two options. You can file in arbitration as required, or you can argue that the arbitration clause is void because the underlying loan contract is void under Georgia usury law.
Step 5: Contact an attorney or file yourself
Consumer rights attorneys in Georgia often take these cases on contingency, meaning they get paid only if you win. Small claims court lets you represent yourself.
Filing a complaint with the Georgia Department of Banking and Finance and the CFPB costs nothing and creates a paper trail that strengthens your legal position.
NetCredit Complaints from Georgia Borrowers
Georgia borrowers have filed hundreds of complaints against NetCredit with state and federal agencies. The complaints paint a consistent picture of confusion, frustration, and financial harm.
The most common themes in Georgia complaints include:
- Unclear total cost: Borrowers say they did not understand how much they would end up paying in total until months into repayment
- Interest eating payments alive: Monthly payments of $200 to $400 where only $20 to $50 goes toward the principal
- Difficulty reaching customer service: Long hold times, unhelpful responses, and refusal to negotiate terms
- Aggressive collection practices: Repeated calls, emails, and letters when payments are late, sometimes within days of a missed payment
- Inability to pay off early without penalty: Some borrowers report confusion about prepayment penalties or how early payoff amounts are calculated
One recurring Georgia complaint describes this pattern: a borrower takes out a $2,500 loan, makes 18 months of payments totaling $4,200, and still owes $2,100 on the principal. That means the borrower paid $4,200 and reduced their debt by only $400.
The Georgia Department of Banking and Finance accepts complaints through its online portal. Every complaint filed adds to the regulatory record. When enough complaints stack up, state regulators are more likely to open formal investigations.
The Better Business Bureau shows NetCredit with a pattern of similar complaints nationwide, with Georgia ranking among the top states for complaint volume relative to population.
NetCredit CFPB Complaints and Federal Actions
The Consumer Financial Protection Bureau has received thousands of complaints about NetCredit nationwide, with Georgia ranking as one of the higher-volume states. These federal complaints carry significant weight because the CFPB has enforcement authority over online lenders.
As of 2025, the CFPB complaint database shows common issues reported by NetCredit borrowers:
- Charged fees or interest not expected
- Problem with the payoff process
- Threatened or actually filed negative credit information
- Difficulty getting information about the loan
- Predatory loan terms
The CFPB has not filed a formal enforcement action against NetCredit or Enova International specifically for Georgia lending as of early 2026. However, the bureau has taken action against similar online lenders, resulting in millions of dollars in refunds to borrowers.
| CFPB Action Against Similar Lenders | Year | Result |
|---|---|---|
| Elevate Credit (Rise/Elastic) | 2023 | $38 million refund ordered |
| CashCall Inc. | 2016 | $10.3 million penalty |
| Think Finance | 2017 | $43 million disgorgement |
| Marlin Capital (debt buyer) | 2024 | $3.2 million redress |
These precedents matter. When the CFPB sees a pattern of harm, it acts. The volume of NetCredit complaints from Georgia borrowers creates exactly the kind of pattern the bureau investigates.
Filing a CFPB complaint takes about 15 minutes online. The bureau forwards your complaint to NetCredit and requires a response within 15 days. Every complaint becomes part of the public record.
Key Takeaway: The CFPB has penalized lenders with practices similar to NetCredit’s, ordering tens of millions in refunds. Georgia borrowers should file CFPB complaints to strengthen the regulatory case.
Enova International Lawsuit and Georgia Connections
Enova International is the parent company behind NetCredit. It trades on the New York Stock Exchange under the ticker ENVA and reported $1.5 billion in revenue in its 2024 fiscal year. Any lawsuit against NetCredit in Georgia ultimately traces back to Enova.
Enova operates several lending brands, including:
- NetCredit: Personal loans and lines of credit
- CashNetUSA: Payday loans and installment loans
- Headway Capital: Small business lines of credit (discontinued)
The company has faced legal challenges in multiple states. State attorneys general in California, Illinois, Virginia, and New York have all examined Enova’s lending practices at various points. Georgia’s investigation into NetCredit’s operations fits this broader pattern.
From a legal strategy perspective, suing Enova International rather than just NetCredit can matter. Enova has the deep pockets. It is the company making the business decisions about interest rates, lending criteria, and which states to operate in.
Georgia courts can assert jurisdiction over Enova because the company actively conducts business in the state through NetCredit. Enova profits from Georgia borrowers, advertises to Georgia consumers, and collects payments from Georgia bank accounts.
The company’s 2024 SEC filings acknowledge legal and regulatory risks associated with state lending laws. That acknowledgment tells you something important: Enova knows its lending model is legally vulnerable.
NetCredit Georgia Borrower Rights in 2026
Georgia borrowers who took out NetCredit loans have specific legal rights under both state and federal law. These rights exist whether or not a class action is certified and regardless of what your loan agreement says.
Your rights as a Georgia borrower include:
- Right to dispute the loan under Georgia usury law. If the interest rate exceeds 7% annually, you may have grounds to void the contract
- Right to recover double interest paid. O.C.G.A. 7-4-10 provides this remedy for usurious loans
- Right to file complaints. With the CFPB, Georgia Department of Banking and Finance, and the Georgia Attorney General’s office
- Right to accurate disclosures. Under the federal Truth in Lending Act, NetCredit must clearly disclose APR, total finance charges, and payment schedules
- Right to fair debt collection. Under the Fair Debt Collection Practices Act and Georgia’s Fair Business Practices Act
- Right to sue. In small claims court, superior court, or through arbitration
| Right | Law or Regulation | What It Protects |
|---|---|---|
| Usury protection | O.C.G.A. 7-4-2 | Caps interest at 7% annually |
| Double recovery | O.C.G.A. 7-4-10 | Allows 2x interest refund |
| Disclosure rights | Truth in Lending Act | Requires clear APR disclosure |
| Collection protection | FDCPA | Limits harassment, misrepresentation |
| Consumer protection | GA Fair Business Practices Act | Prohibits deceptive trade practices |
One right that many borrowers overlook is the right to request a full accounting from NetCredit. You can demand a detailed breakdown of every payment, showing exactly how much went to principal, interest, and fees. This information is essential for calculating your potential legal claim.
Key Takeaway: Georgia law gives borrowers powerful tools against usurious lenders, including the ability to void the loan entirely and recover double the interest already paid.
NetCredit Loan Forgiveness in Georgia
Loan forgiveness from NetCredit is not automatic, but Georgia borrowers may achieve partial or full loan cancellation through legal action, regulatory intervention, or settlement. The path depends on your specific situation.
There are several ways Georgia borrowers could see their NetCredit loans forgiven:
Court-ordered voiding: If a Georgia court finds that your NetCredit loan violates state usury law, the court can declare the loan void ab initio, meaning it is treated as if it never existed. You would owe nothing further, and you could recover interest already paid.
Settlement forgiveness: In lending settlements, companies often agree to forgive outstanding balances for affected borrowers. This happened in the Think Finance case, where borrowers saw up to 100% loan forgiveness in certain states.
Regulatory action: If the CFPB or Georgia regulators issue a consent order against NetCredit, it could include mandatory debt relief for Georgia borrowers.
| Forgiveness Path | Likelihood in 2026 | Potential Relief |
|---|---|---|
| Court voiding (individual suit) | Moderate to High | 100% balance forgiveness + refunds |
| Settlement (group action) | Moderate | 25% to 100% balance forgiveness |
| CFPB enforcement | Moderate | Refunds + balance adjustments |
| State AG action | Low to Moderate | Balance forgiveness + fines |
| Voluntary (NetCredit offer) | Very Low | Minimal, if any |
Be aware of tax implications. Forgiven debt over $600 is generally treated as taxable income by the IRS. You would receive a 1099-C form for the forgiven amount. Plan accordingly.
Document everything now. The borrowers who get the best outcomes are the ones who kept their records organized from the start.
Can You Stop Paying NetCredit?
Stopping payments to NetCredit is a risky move that can have serious consequences, but it may be strategically justified in certain situations. The answer depends on whether you plan to take legal action simultaneously.
If you simply stop paying without taking any legal steps, here is what typically happens:
- Days 1 to 30: NetCredit contacts you by phone, email, and text about the missed payment
- Days 31 to 60: Late fees accumulate. Interest continues to compound on the full balance
- Days 61 to 90: NetCredit may report the delinquency to credit bureaus, damaging your credit score by 50 to 100+ points
- Days 90 to 180: The account may be sent to an internal collections department or sold to a third-party debt collector
- After 180 days: Potential lawsuit from NetCredit or a debt buyer to obtain a judgment against you
However, if you stop paying as part of a legal strategy, the picture changes. If your attorney has filed a claim arguing the loan is void under Georgia usury law, a court may issue an injunction preventing NetCredit from collecting or reporting negative information while the case proceeds.
| Action | Risk Level | Potential Benefit |
|---|---|---|
| Stop paying, do nothing else | High | Saves money short-term, damages credit |
| Stop paying, file legal claim | Moderate | Creates leverage, may lead to voiding |
| Keep paying, file legal claim | Low risk | Protects credit, seek refund after ruling |
| Negotiate directly with NetCredit | Low to Moderate | May get reduced payoff, no guarantee |
Think of it like a tenant withholding rent from a landlord who refuses to fix a broken furnace. You have the right to withhold, but only if you follow the proper legal process while doing it.
The safest approach is to keep paying while pursuing legal action, then seek a refund or credit after a favorable ruling. But if you genuinely cannot afford the payments, filing a legal challenge while communicating your position to NetCredit in writing creates a stronger defense.
NetCredit Debt Collection Practices in Georgia
NetCredit’s debt collection practices in Georgia must comply with both federal and state law, and borrowers have reported multiple instances where those practices crossed the line. The Fair Debt Collection Practices Act and Georgia’s own collection statutes set clear boundaries.
Under federal law, debt collectors cannot:
- Call before 8 a.m. or after 9 p.m.
- Use threatening, abusive, or obscene language
- Misrepresent the amount owed
- Contact you at work if you tell them to stop
- Discuss your debt with third parties (neighbors, coworkers, family)
- Threaten legal action they do not intend to take
Georgia borrowers have reported NetCredit and its third-party collectors engaging in several problematic behaviors:
- Calling multiple times per day, sometimes within minutes of each other
- Threatening to garnish wages without having obtained a court judgment first
- Contacting borrowers by text message without prior consent
- Reporting debts to credit bureaus that borrowers dispute as usurious and void
Under Georgia law (O.C.G.A. 7-4-10), if the underlying loan is usurious, the debt itself may be uncollectable. That means any attempt to collect on a void debt could violate Georgia’s Fair Business Practices Act and the federal FDCPA simultaneously.
| Collection Violation | Federal Fine | Georgia Remedy |
|---|---|---|
| Harassment (excessive calls) | Up to $1,000 per violation | Actual damages + attorney fees |
| False threats (wage garnishment) | Up to $1,000 per violation | Actual damages + punitive damages |
| Reporting disputed void debt | Up to $1,000 per violation | Credit report correction + damages |
If NetCredit or a collector contacts you about a Georgia loan, ask for the debt to be validated in writing. Under federal law, the collector must provide this within 5 days of initial contact. If you believe the debt is usurious and void, send a written dispute and keep a copy.
Key Takeaway: If your NetCredit loan violates Georgia’s usury laws, any attempt to collect on that debt may itself be illegal, giving you additional legal claims and potential damages.
Frequently Asked Questions
Can I sue NetCredit in Georgia for charging illegal interest rates?
Yes, Georgia borrowers can sue NetCredit for charging interest rates that exceed the state’s usury caps.
Under O.C.G.A. 7-4-2, the maximum contract rate is 7% per year.
Courts may void the loan and award you double the interest you paid under O.C.G.A. 7-4-10.
Is there a NetCredit class action lawsuit in 2026?
No certified class action exists specifically for Georgia NetCredit borrowers as of early 2026.
However, individual lawsuits and mass arbitration efforts are active and growing.
NetCredit’s mandatory arbitration clause has been the main barrier to class certification.
How much money could I get from a NetCredit settlement in Georgia?
Based on similar lending settlements, Georgia borrowers could recover $500 to $3,000 in interest refunds.
Outstanding loan balances may be forgiven partially or entirely.
Actual amounts depend on your loan terms, total interest paid, and the final settlement or court ruling.
Does Georgia’s usury law make my NetCredit loan void?
Georgia courts can declare a usurious loan void ab initio, meaning it is treated as though it never existed.
If your NetCredit loan charges more than 7% annual interest, it likely qualifies as usurious under Georgia law.
A void loan means you owe nothing further and may recover double the interest already paid.
What happens if I stop paying NetCredit in Georgia?
Stopping payments without legal action can result in credit damage, collection calls, and a potential lawsuit from NetCredit.
If you stop paying while pursuing a legal claim that the loan is void, you may have a valid defense.
The safest approach is to consult a consumer rights attorney before halting payments.
The NetCredit lawsuit situation in Georgia is real, growing, and backed by some of the strongest usury laws in the country. Borrowers who paid triple-digit APRs have powerful legal tools at their disposal.
If you borrowed from NetCredit in Georgia, start by gathering your loan documents and payment records. File complaints with the CFPB and Georgia Department of Banking and Finance. Consider reaching out to a consumer rights attorney who handles usury cases.
2026 is shaping up to be a pivotal year for this fight. Do not sit on the sideline when you might be owed thousands.







