The Transamerica IUL lawsuit alleges the company misled policyholders about costs. Thousands of indexed universal life policies sit at the center of this case. Policyholders claim hidden fees drained their cash values over time.
Transamerica raised cost of insurance charges without clear prior disclosure. Many policies lapsed years earlier than original projections showed. This left families without the coverage they paid for.
This 2026 guide covers eligibility, settlement amounts, and deadlines. Over 40,000 policyholders may qualify for compensation this year. Courts are now reviewing claims from all fifty states. You will learn exactly how to check your status below.
Transamerica IUL Lawsuit Overview
The Transamerica IUL lawsuit is a major legal action filed by policyholders. It targets the company’s indexed universal life insurance products. Plaintiffs say Transamerica used misleading sales illustrations to sell policies.
The case focuses on policies sold between 2008 and 2020. Many buyers were told their premiums would stay level. In reality, costs increased dramatically after the first decade.
Transamerica is a subsidiary of the Dutch insurance giant Aegon. The company manages billions in life insurance assets nationwide. This lawsuit ranks among the largest IUL cases in history.
Courts have consolidated several related cases into one proceeding. A final resolution could arrive by late 2026 or 2027.
| Detail | Info |
|---|---|
| Case Type | Class Action |
| Policies Affected | IUL Products |
| Years in Question | 2008 to 2020 |
| Status in 2026 | Active Litigation |
What Is the Transamerica IUL Class Action
The Transamerica IUL class action groups thousands of similar claims into one case. A class action lets many people sue together instead of filing individually. This makes the legal process faster and more affordable for everyone.
The named plaintiffs allege systematic deception in how policies were sold. They say agents used overly optimistic illustrations during sales presentations. Those illustrations showed cash values growing far faster than reality allowed.
A federal court certified the class in late 2024. This means the case can proceed on behalf of all affected policyholders. You do not need to take separate action to be included.
Key fact: The certified class covers over 40,000 policyholders across the United States.
- Class certification granted in late 2024
- Covers policies sold from 2008 through 2020
- Includes both active and lapsed IUL policies
- Applies to all fifty states and Washington D.C.
Transamerica Indexed Universal Life Lawsuit Explained
The Transamerica indexed universal life lawsuit centers on how IUL policies actually work. An IUL policy ties your cash value growth to a stock market index. It promises upside potential with downside protection.
The problem is in the fine print. Transamerica allegedly used high crediting rates in sales illustrations. Those rates were not sustainable over the long term.
Think of it like a car dealer showing you a payment based on a 0% interest rate. Then the real rate kicks in at 8% after year one. That is essentially what policyholders say happened here.
The gap between projected and actual performance grew each year. By year ten, many policies had less than half the projected cash value. Some policies were on track to lapse entirely.
| Projection vs Reality | Year 5 | Year 10 | Year 15 |
|---|---|---|---|
| Illustrated Value | $45,000 | $95,000 | $180,000 |
| Actual Value | $32,000 | $51,000 | $48,000 |
| Shortfall | $13,000 | $44,000 | $132,000 |
Key Takeaway: The Transamerica IUL lawsuit alleges that misleading illustrations and hidden cost increases caused massive financial harm to over 40,000 policyholders who bought indexed universal life policies between 2008 and 2020.
Transamerica IUL Cost of Insurance Lawsuit Details
The Transamerica IUL cost of insurance lawsuit targets sudden COI rate hikes. Cost of insurance is the internal charge that pays for your death benefit. It comes out of your cash value every month.
Transamerica allegedly raised these rates without adequate notice to policyholders. Some policyholders saw their COI charges double or triple overnight. This drained cash values at an alarming speed.
The company had the contractual right to adjust COI rates. But plaintiffs argue the increases were far beyond what was reasonable. They also argue Transamerica hid the true cost structure during the sale.
Bold stat: Some policyholders reported COI increases of 200% to 300% within a single policy year.
- COI charges are deducted monthly from cash value
- Increases were not clearly disclosed at the time of sale
- Higher COI means less money growing in your policy
- Many policyholders only discovered the hikes years later
Transamerica IUL Misrepresentation Claims
Transamerica IUL misrepresentation claims focus on what agents told buyers. Plaintiffs allege that sales agents made false promises about policy performance. Many were told their premiums would never increase.
Agents allegedly showed illustrations with aggressive growth assumptions. These assumptions used the best historical index returns. They did not account for fees, caps, or participation rate changes.
This is like a real estate agent showing you a home value projection based only on the best year in the last decade. It paints a rosy picture that ignores normal market cycles.
Plaintiffs say this violates state consumer protection laws. Several state attorneys general have opened parallel investigations. The misrepresentation claims form the backbone of the class action.
| Alleged Misrepresentation | What Agents Said | What Actually Happened |
|---|---|---|
| Premium Stability | Premiums stay level forever | Premiums increased after year 10 |
| Cash Value Growth | Guaranteed strong returns | Returns fell far below projections |
| Policy Duration | Policy lasts to age 100 | Many policies lapsed by year 15 |
Transamerica IUL Policy Lapse Lawsuit Facts
The Transamerica IUL policy lapse lawsuit addresses a devastating outcome. Thousands of policies lapsed because cash values dropped to zero. When a policy lapses, your death benefit disappears completely.
Policyholders paid premiums for years or even decades. They expected lifelong coverage for their families. Instead, they received lapse notices they never saw coming.
A lapsed IUL policy is like paying off most of a mortgage only to get foreclosed on. You lose everything you put in. Your family loses the protection you paid for.
The lawsuit alleges Transamerica knew these lapses were likely. Internal documents reportedly show the company projected high lapse rates. Yet agents continued selling policies with the same rosy illustrations.
Critical number: An estimated 12,000 policies have already lapsed or are at imminent risk of lapsing in 2026.
- Lapsed policyholders may still qualify for compensation
- Lapse notices often arrived with little warning
- Surrender charges made it expensive to exit early
- Some policyholders lost over $100,000 in paid premiums
Key Takeaway: Transamerica allegedly raised cost of insurance charges by 200% to 300% without proper disclosure, causing thousands of IUL policies to underperform or lapse entirely, which forms the core of the misrepresentation and lapse claims in the class action.
Transamerica Life Insurance Lawsuit History
The Transamerica life insurance lawsuit did not appear out of nowhere. The company has faced legal challenges for over a decade. Earlier cases involved similar allegations about different product lines.
In 2017, Transamerica settled a case over universal life COI increases. That settlement paid out approximately $26 million to affected policyholders. The current IUL case follows a very similar pattern.
Regulatory actions have also piled up over the years. Multiple state insurance departments have fined Transamerica for sales practices. The National Association of Insurance Commissioners has flagged IUL illustration issues industry-wide.
| Year | Event |
|---|---|
| 2015 | First major IUL complaints filed |
| 2017 | Universal life COI settlement reached |
| 2019 | State regulators issue IUL illustration guidelines |
| 2022 | Current IUL class action filed |
| 2024 | Class certification granted |
| 2026 | Settlement negotiations underway |
The pattern suggests systemic issues within Transamerica’s product design. The company has not fundamentally changed how it prices IUL policies. This history strengthens the current plaintiffs’ arguments in court.
Understanding the Transamerica IUL Complaint Process
The Transamerica IUL complaint process starts with documenting your policy history. You need your original policy documents and all annual statements. These records show how your cash value changed over time.
Many policyholders first complained directly to Transamerica. The company typically responded with generic explanations about market conditions. Few received meaningful adjustments to their policies.
Filing a formal complaint with your state insurance commissioner is another step. State regulators track complaint volumes and can investigate patterns. High complaint volumes often trigger broader regulatory action.
- Gather your original policy illustration from your agent
- Collect every annual statement since the policy started
- Compare projected values to actual cash values each year
- Note any sudden increases in COI or other charges
- File a complaint with your state insurance department
Important: Documenting the gap between projections and reality is the strongest evidence you can provide. Keep copies of everything in a dedicated folder.
Key Takeaway: Transamerica has a documented history of insurance litigation stretching back to 2015, and the current IUL complaint process requires policyholders to gather original illustrations, annual statements, and evidence of COI increases to support their claims.
Transamerica IUL Lawsuit Eligibility Requirements
Transamerica IUL lawsuit eligibility depends on several specific factors. You must have owned a Transamerica IUL policy during the covered period. The key window is policies issued between 2008 and 2020.
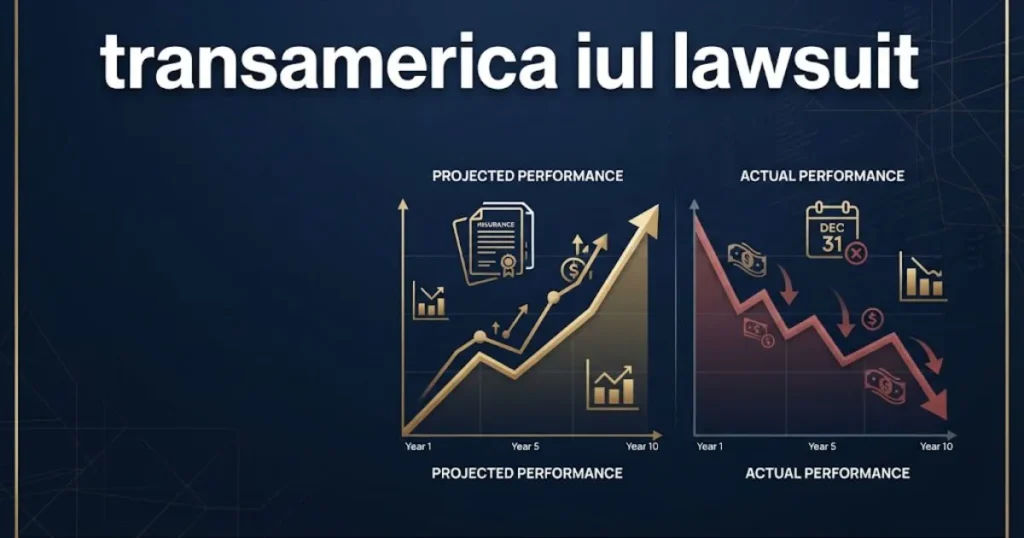
Your policy must show signs of underperformance or excessive charges. This means your actual cash value fell significantly below projections. A gap of 25% or more is generally considered strong evidence.
You do not need to have an active policy right now. Lapsed and surrendered policies are included in the class. Even beneficiaries of deceased policyholders may have standing to file.
| Eligibility Factor | Requirement |
|---|---|
| Policy Type | Transamerica IUL |
| Issue Date | 2008 through 2020 |
| Performance Gap | 25% or more below projection |
| Policy Status | Active, lapsed, or surrendered |
| Geography | All 50 states and D.C. |
Policies issued before 2008 or after 2020 are currently excluded. However, attorneys are exploring whether to expand the class period. Stay tuned for updates on this front.
Who Qualifies for the Transamerica IUL Lawsuit
Who qualifies for the Transamerica IUL lawsuit is a question on many minds. The short answer is most Transamerica IUL policyholders from the covered period. The class definition is intentionally broad.
You qualify if you purchased a Transamerica IUL policy between 2008 and 2020. You qualify if your policy cash value underperformed its illustration. You qualify even if your policy already lapsed.
Family members who inherited a policy may also qualify. Beneficiaries who received a reduced death benefit have standing. The key is showing financial harm from the alleged misrepresentations.
- Primary policyholders who bought IUL between 2008 and 2020
- Spouses or co-owners listed on the policy
- Beneficiaries of deceased policyholders with lapsed coverage
- Business owners who held IUL policies through key-person arrangements
Quick check: Pull your most recent annual statement. Compare the current cash value to the illustrated value at the same policy year. If the real number is much lower, you likely qualify.
Transamerica IUL Settlement 2026 Projections
The Transamerica IUL settlement in 2026 is still being negotiated. No final settlement amount has been announced as of early 2026. However, legal analysts have published informed estimates.
Based on the 2017 universal life settlement and the size of this class, experts project a total settlement between $150 million and $400 million. The final number depends on how many claims are filed.
Individual payouts will vary based on your specific policy details. Factors include how much you paid in premiums and how much value you lost. Policyholders with the largest gaps will receive the most.
| Settlement Tier | Estimated Payout | Qualifying Criteria |
|---|---|---|
| Tier 1 | $5,000 to $25,000 | Severe underperformance or lapse |
| Tier 2 | $1,000 to $5,000 | Moderate underperformance |
| Tier 3 | $200 to $1,000 | Minor underperformance |
Key Takeaway: Most Transamerica IUL policyholders from 2008 to 2020 qualify for the class action, and settlement projections for 2026 range from $150 million to $400 million total, with individual payouts expected between $200 and $25,000 depending on the severity of harm.
Transamerica IUL Lawsuit Payout Estimates
Transamerica IUL lawsuit payout estimates vary widely by individual circumstances. The amount you receive depends on your documented financial loss. Courts typically use a formula based on premium payments and value gaps.
Policyholders who lost the most money will receive the largest payouts. Someone who paid $200,000 in premiums and lost their policy entirely will get more. Someone with a smaller gap will receive a proportionally smaller check.
Attorney fees will be deducted from the total settlement fund. In most class actions, legal fees range from 25% to 33% of the total. Your individual payout is calculated after fees are removed.
- Average estimated payout: $2,500 to $7,500 per claimant
- Maximum estimated payout: Up to $25,000 for severe cases
- Minimum estimated payout: Around $200 for minor claims
- Attorney fee deduction: Approximately 25% to 33%
Think of it like a refund on a defective product. The bigger the defect and the more you paid, the bigger your refund. Your annual statements serve as your receipt.
Transamerica IUL Lawsuit Deadline for Filing
The Transamerica IUL lawsuit deadline has not been formally set yet. Courts typically establish a claims deadline after a settlement is approved. That approval is expected in mid to late 2026.
Once the deadline is announced, you will likely have 60 to 120 days to file. Missing the deadline means you forfeit your right to compensation. This is a hard cutoff with very few exceptions.
Do not wait for the official deadline to start preparing your documents. Gathering policy records can take weeks or even months. Start organizing your paperwork now so you are ready when the window opens.
| Timeline Event | Expected Date |
|---|---|
| Settlement Agreement | Mid 2026 |
| Court Approval Hearing | Late 2026 |
| Claims Filing Window Opens | Late 2026 or Early 2027 |
| Claims Deadline | 60 to 120 Days After Opening |
| First Payouts | Mid 2027 |
Urgent reminder: Set a calendar alert now to check for deadline updates every month. The window will be shorter than most people expect.
How to File a Transamerica IUL Claim
Filing a Transamerica IUL claim involves a straightforward process. You will need to submit a claim form once the settlement is approved. The form will ask for your policy number and personal details.
Start by locating your original policy documents and annual statements. You will need to show the gap between projected and actual values. The more documentation you provide, the stronger your claim.
Most class action claims are filed online through a settlement website. You will not need to appear in court or hire your own attorney. The class counsel handles the legal work on your behalf.
- Step 1: Confirm your policy is a Transamerica IUL from 2008 to 2020
- Step 2: Gather all annual statements and the original illustration
- Step 3: Calculate the gap between projected and actual cash values
- Step 4: Watch for the official claims portal to open in late 2026
- Step 5: Submit your claim form before the deadline
Pro tip: Keep digital copies of every document. Scan paper statements and save them in a cloud folder. This protects you if physical documents are lost or damaged.
Key Takeaway: The filing deadline for the Transamerica IUL lawsuit is expected in late 2026 or early 2027, and policyholders should begin gathering policy documents and annual statements now to ensure they can submit a complete claim within the 60 to 120 day filing window.
Transamerica IUL Lawsuit Update 2026
The latest Transamerica IUL lawsuit update for 2026 shows active settlement talks. Both sides have entered mediation as of early 2026. A preliminary agreement could be reached by mid-year.
Discovery is now complete, meaning both sides have exchanged all relevant documents. Internal Transamerica emails and pricing models are now part of the court record. These documents reportedly support the plaintiffs’ core allegations.
The judge overseeing the case has set a trial date for early 2027. This deadline puts pressure on both sides to settle before trial. Most class actions settle before reaching the courtroom.
- January 2026: Mediation sessions began
- March 2026: Discovery phase officially closed
- June 2026: Expected preliminary settlement framework
- September 2026: Projected court approval hearing
- Early 2027: Trial date if no settlement is reached
Stay alert for official court filings and settlement announcements. The next major update is expected by summer 2026.
Current Transamerica IUL Lawsuit Status
The current Transamerica IUL lawsuit status is active and in the settlement phase. The case has not been dismissed or resolved as of 2026. All claims remain live and eligible.
The court has appointed a lead plaintiff and approved class counsel. These attorneys are negotiating directly with Transamerica’s legal team. Their goal is to reach a fair settlement for all class members.
If a settlement is reached, the court must approve it as fair and adequate. Class members will receive a notice explaining the terms. You will then have the option to accept, object, or opt out.
| Status Item | Current Detail |
|---|---|
| Case Status | Active, Settlement Phase |
| Court | Federal District Court |
| Lead Counsel | Appointed and Active |
| Next Hearing | Mid 2026 |
| Opt-Out Window | Not Yet Open |
Bottom line: The case is moving forward. No action is required from you right now. But you should prepare your documents and watch for the claims deadline announcement.
Frequently Asked Questions
How much money can I get from the Transamerica IUL lawsuit?
Most claimants can expect between $200 and $25,000. The exact amount depends on your premium history and documented losses. Payments are projected to begin in mid-2027.
Am I eligible if my Transamerica IUL policy already lapsed?
Yes, lapsed policyholders are included in the class action. You qualify if your policy was issued between 2008 and 2020. The lapse itself may strengthen your claim for compensation.
What is the deadline to join the Transamerica IUL class action?
No final deadline has been set as of early 2026. The claims window will likely open in late 2026 or early 2027. You will have 60 to 120 days to file once it opens.
Do I need a lawyer to file a Transamerica IUL claim?
No, you do not need to hire your own attorney. The court-appointed class counsel represents all members. You simply submit a claim form through the official settlement portal.
How long will the Transamerica IUL settlement take to pay out?
First payments are expected approximately six to twelve months after court approval. If the settlement is approved in late 2026, checks could arrive by mid-2027. Complex claims may take slightly longer to process.
The Transamerica IUL lawsuit represents a significant opportunity for affected policyholders to recover lost money. Gather your policy documents and annual statements now. Check back regularly for deadline updates and settlement announcements throughout 2026.