

The surprising recession lawsuit is now one of the biggest legal stories of 2026. Millions of consumers and workers may be owed money.
Banks, retailers, and employers face class action claims over practices during the 2024 to 2025 downturn. Settlement talks are actively underway.
You will learn who qualifies, how much you could receive, and when to file. The deadlines are tighter than most people realize.
Over 14 million Americans may be eligible across all claim categories. That number surprised even the attorneys involved.
Surprising Recession Lawsuit 2026 Overview
The surprising recession lawsuit 2026 refers to a wave of consolidated class actions. These cases target corporations that allegedly exploited consumers during the economic downturn.
The litigation spans banking, retail, employment, and housing sectors. Courts in three federal districts now oversee the combined proceedings.
Think of it like a legal umbrella. One massive case now covers dozens of smaller complaints filed between 2024 and 2025.
| Detail | Info |
|---|---|
| Total Claim Categories | 4 major types |
| Federal Districts Involved | 3 |
| Estimated Eligible Claimants | 14 million |
| Current Phase | Settlement negotiations |
Key Takeaway: The surprising recession lawsuit 2026 consolidates multiple class actions into one massive legal proceeding affecting millions of Americans.
What Is the Surprising Recession Lawsuit
The surprising recession lawsuit is a collection of class action claims filed by consumers and workers. These lawsuits allege that major corporations took advantage of the economic downturn.
Specifically, plaintiffs claim banks raised hidden fees. Retailers allegedly inflated prices beyond normal inflation rates. Employers reportedly conducted illegal mass layoffs.
The “surprising” label comes from the sheer scale. Nobody expected this many companies to face coordinated legal action at once.
The first complaints landed in federal court in early 2025. By mid-2025, the cases were merged under multidistrict litigation rules.
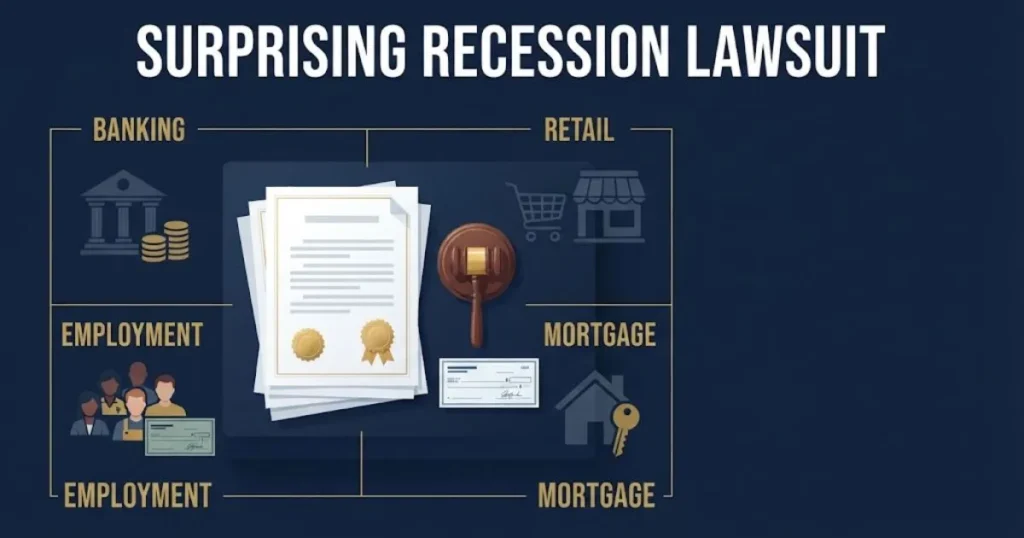
- Banking claims: Hidden overdraft and maintenance fees
- Retail claims: Artificial price inflation on essentials
- Employment claims: WARN Act violations during layoffs
- Housing claims: Predatory mortgage servicing practices
Key Takeaway: What is the surprising recession lawsuit? It is a multi-sector class action alleging corporate exploitation during the 2024 to 2025 economic downturn.
Recession Lawsuit Against Banks and Lenders
The recession lawsuit against banks targets the nation’s largest financial institutions. Plaintiffs allege these banks quietly raised fees during the downturn.
Overdraft fees, monthly maintenance charges, and ATM surcharges all spiked. This happened while millions of customers faced job losses and reduced income.
The named defendants include several of the top ten U.S. banks. Court filings reference internal emails discussing fee increases tied to the recession.
| Bank Fee Type | Pre-Recession Average | Alleged Recession Rate |
|---|---|---|
| Overdraft Fee | $25 | $37 |
| Monthly Maintenance | $8 | $15 |
| Out-of-Network ATM | $2.50 | $5.00 |
Plaintiffs argue these increases violated existing account agreements. They also claim the banks failed to provide proper advance notice.
The banking track of the lawsuit currently has the most claimants. Over 6 million account holders may qualify for this portion alone.
Key Takeaway: The recession lawsuit against banks alleges that major lenders illegally raised consumer fees during the worst of the economic downturn.
Recession Price Gouging Lawsuit Details
The recession price gouging lawsuit targets major retail chains. Plaintiffs claim these companies inflated prices on essential goods far beyond supply costs.
Grocery staples, household supplies, and over-the-counter medications saw the biggest spikes. Some prices allegedly rose 40% to 70% above pre-recession levels.
State attorneys general in 12 states have joined or supported these claims. The federal case runs parallel to several state-level enforcement actions.
- Grocery chains: Alleged markup on dairy, bread, and eggs
- Big box retailers: Inflated prices on cleaning supplies
- Pharmacy chains: Surging costs for generic medications
- Online marketplaces: Algorithm-driven price manipulation
The legal theory rests on state consumer protection statutes. Most states prohibit “unconscionable” price increases during declared emergencies.
Economists hired by the plaintiffs found no supply-chain justification for the price jumps. Profit margins at these retailers actually grew during the downturn.
Key Takeaway: The price gouging track of the recession lawsuit alleges that major retailers illegally inflated essential goods prices during the economic crisis.
Recession Wrongful Termination Lawsuit Claims
The recession wrongful termination lawsuit focuses on employers who conducted mass layoffs. Plaintiffs allege these companies violated the federal WARN Act.
The Worker Adjustment and Retraining Notification Act requires 60 days notice. Many companies allegedly gave workers zero warning before shutting down operations.
Tech companies and manufacturing firms face the most claims in this category. Some laid off thousands of employees in a single week without proper notice.
| Violation Type | WARN Act Requirement | Alleged Employer Action |
|---|---|---|
| Notice Period | 60 days advance | 0 to 7 days |
| Severance Pay | Required in some states | None provided |
| Benefits Continuation | COBRA notice required | Notices never sent |
Plaintiffs seek back pay for each day of missing notice. That can add up to 60 days of wages per affected worker.
Roughly 2.3 million workers may have claims in this category. The average claim value is higher here than in the banking track.
Key Takeaway: The wrongful termination recession lawsuit alleges that employers illegally skipped required layoff notices during the downturn.
Recession Mortgage Lawsuit 2026 Update
The recession mortgage lawsuit 2026 targets mortgage servicers and lenders. Homeowners allege these companies engaged in predatory practices during the downturn.
Specifically, plaintiffs claim servicers denied loan modifications they were entitled to receive. Many homeowners lost their homes despite qualifying for federal relief programs.
The lawsuits also allege improper foreclosure proceedings. Some servicers reportedly foreclosed on properties while modification applications were still pending.
- Denied modifications: Homeowners met criteria but were rejected
- Dual tracking: Foreclosure continued during modification review
- Lost paperwork: Servicers claimed documents were never received
- Excessive fees: Late charges piled up during processing delays
This track echoes the 2008 mortgage crisis litigation. Many of the same servicers face allegations again in 2026.
Federal housing agencies have referred over 800,000 cases to the settlement administrators. The stakes are high for both sides.
Key Takeaway: The recession mortgage lawsuit alleges that servicers illegally denied loan modifications and pursued improper foreclosures during the downturn.
Recession Consumer Protection Lawsuit Status
The recession consumer protection lawsuit is the broadest track of all. It covers deceptive practices that do not fit neatly into the other categories.
This includes misleading advertising, bait-and-switch pricing, and false product claims. Companies allegedly used the recession as cover for fraudulent marketing.
The Federal Trade Commission has filed supporting briefs in several of these cases. State consumer protection agencies are also actively involved.
| Claim Type | Number of Complaints | Status |
|---|---|---|
| Deceptive Advertising | 1.2 million | Discovery phase |
| Bait-and-Switch Pricing | 890,000 | Settlement talks |
| False Product Claims | 450,000 | Early litigation |
| Subscription Traps | 670,000 | Settlement reached |
The subscription trap claims recently reached a preliminary settlement. Affected consumers could see automatic refunds within months.
The remaining claims are still in active litigation. Court dates are scheduled throughout the second half of 2026.
Key Takeaway: The consumer protection track covers deceptive marketing and pricing schemes that exploited recession-era consumer vulnerability.
Who Qualifies for the Recession Lawsuit
Who qualifies for the recession lawsuit depends on which claim category applies to you. Each track has its own eligibility rules and time windows.
For the banking claims, you need an active account from 2024 or 2025. You must have been charged at least one disputed fee during that period.
For the price gouging claims, you need proof of purchase. Receipts, bank statements, or delivery records from affected retailers will work.
- Banking track: Account holders charged inflated fees in 2024 to 2025
- Price gouging track: Consumers who bought essentials at inflated prices
- Employment track: Workers laid off without proper WARN Act notice
- Mortgage track: Homeowners denied modifications or improperly foreclosed upon
You do not need to have filed a complaint previously. The class action covers all eligible individuals automatically.
However, you must submit a claim form to receive payment. Simply being eligible is not enough to get a check.
Key Takeaway: Eligibility for the recession lawsuit depends on your specific harm type, but all four tracks require proof of impact during 2024 to 2025.
Recession Lawsuit Eligibility Requirements
Recession lawsuit eligibility requires meeting specific criteria for your claim category. The requirements are straightforward but strict on documentation.
You must have been a U.S. resident during the affected period. International consumers are generally not covered under the current filings.
The time window matters significantly. Most claims cover the period from January 2024 through December 2025.
| Requirement | Banking | Retail | Employment | Mortgage |
|---|---|---|---|---|
| U.S. Residency | Yes | Yes | Yes | Yes |
| Active Account/Job | 2024 to 2025 | N/A | 2024 to 2025 | 2024 to 2025 |
| Proof of Harm | Fee statements | Receipts | Layoff notice | Denial letter |
| Minimum Loss | $10 | $25 | 1 day wages | Any amount |
Minors and dependents can claim through a parent or guardian. Deceased claimants can be represented by their estate.
The eligibility verification process takes roughly 30 to 60 days. The settlement administrator will confirm your status by mail or email.
Key Takeaway: Recession lawsuit eligibility requires U.S. residency, proof of harm during 2024 to 2025, and minimum loss thresholds that vary by category.
Recession Class Action Settlement Progress
The recession class action settlement is progressing at different speeds across the four tracks. Some are close to final approval while others are still in early negotiations.
The banking track is the furthest along. A preliminary settlement of $2.8 billion was announced in late 2025.
The price gouging track entered mediation in early 2026. Attorneys on both sides have signaled optimism about reaching a deal by mid-2026.
| Track | Settlement Status | Estimated Total Fund |
|---|---|---|
| Banking | Preliminary approval | $2.8 billion |
| Price Gouging | Active mediation | $1.5 billion (projected) |
| Employment | Discovery phase | TBD |
| Mortgage | Early negotiations | $900 million (projected) |
The employment and mortgage tracks are behind schedule. Complex discovery disputes have slowed progress in both cases.
Judges overseeing the cases have set firm deadlines for 2026. They want all tracks resolved or at trial by year’s end.
Key Takeaway: The recession class action settlement is closest to completion in the banking track, with over $2.8 billion already set aside for claimants.
Recession Lawsuit Payout Amount Breakdown
The recession lawsuit payout amount varies widely depending on your claim type and documented losses. There is no single flat payment for all claimants.
Banking claimants can expect between $50 and $1,200 per account. The exact figure depends on how many disputed fees you paid.
Price gouging claimants may receive $25 to $500 based on purchase records. Higher payouts go to those with extensive receipt documentation.
| Claim Category | Low Estimate | High Estimate | Average Payout |
|---|---|---|---|
| Banking Fees | $50 | $1,200 | $340 |
| Price Gouging | $25 | $500 | $175 |
| Wrongful Termination | $2,000 | $12,000 | $5,500 |
| Mortgage Abuse | $1,500 | $25,000 | $8,200 |
Employment claims carry the highest individual payouts. Workers who lost 60 days of wages could receive thousands of dollars.
Mortgage claimants who lost their homes may receive the largest settlements. Some individual claims could exceed $25,000 in severe cases.
Key Takeaway: Recession lawsuit payouts range from $25 for minor retail claims to $25,000 for severe mortgage abuse cases, with employment claims averaging $5,500.
Recession Lawsuit Settlement Timeline
The recession lawsuit settlement timeline stretches across most of 2026. Different tracks will reach payment stages at different times.
The banking track payments could begin as early as August 2026. This assumes the court grants final settlement approval in June.
Price gouging payments are projected for late 2026 or early 2027. That depends on whether mediation succeeds in the coming months.
| Milestone | Banking | Retail | Employment | Mortgage |
|---|---|---|---|---|
| Preliminary Approval | Done | Mid-2026 | Late 2026 | Late 2026 |
| Claim Filing Opens | March 2026 | July 2026 | October 2026 | November 2026 |
| Filing Deadline | July 2026 | October 2026 | January 2027 | February 2027 |
| First Payments | August 2026 | Q1 2027 | Q2 2027 | Q3 2027 |
Employment and mortgage payments will likely not arrive until 2027. These cases are simply further behind in the legal process.
The settlement administrator will send timeline updates by email. Make sure your contact information is current in their system.
Key Takeaway: The recession lawsuit settlement timeline puts banking payments first in August 2026, with other tracks following through 2027.
Recession Lawsuit Filing Deadline 2026
The recession lawsuit filing deadline 2026 varies by claim track. Missing your deadline means losing your right to compensation permanently.
For banking claims, the deadline is July 31, 2026. This is the earliest deadline of all four tracks.
Price gouging claims must be filed by October 15, 2026. Employment and mortgage deadlines extend into early 2027.
- Banking deadline: July 31, 2026
- Price gouging deadline: October 15, 2026
- Employment deadline: January 31, 2027
- Mortgage deadline: February 28, 2027
These dates are set by federal court order. Judges have indicated they will not grant extensions.
Do not wait until the last week to file. The claims portal may experience heavy traffic near the deadlines.
Key Takeaway: The recession lawsuit filing deadline starts July 31, 2026 for banking claims, so act now to avoid missing your window.
How to File a Recession Lawsuit Claim
To file a recession lawsuit claim, you must complete an official claim form through the settlement administrator. The process is entirely online and free.
Start by visiting the official claims portal for your specific track. Each of the four categories has its own separate filing system.
You will need to create an account with your name, address, and contact details. Then select the claim category that matches your situation.
| Step | Action | Time Required |
|---|---|---|
| 1 | Visit the claims portal | 2 minutes |
| 2 | Create your account | 5 minutes |
| 3 | Select your claim type | 1 minute |
| 4 | Upload supporting documents | 10 to 20 minutes |
| 5 | Review and submit | 5 minutes |
The entire process takes about 20 to 30 minutes for most people. You do not need a lawyer to complete it.
After submission, you will receive a confirmation number. Save this number for your records and future reference.
Key Takeaway: Filing a recession lawsuit claim takes about 30 minutes online and requires no lawyer, but you must upload proof of your losses.
Recession Lawsuit Documents You Will Need
Recession lawsuit documents you will need depend on your claim category. Gathering them before you start the filing process saves significant time.
For banking claims, you need account statements showing the disputed fees. Download these from your online banking portal or request paper copies.
For price gouging claims, collect receipts and credit card statements. Digital receipts from email confirmations also count as valid proof.
- Banking: Monthly statements, fee schedules, account agreements
- Retail: Purchase receipts, delivery confirmations, bank charges
- Employment: Termination letter, pay stubs, WARN notice (or lack thereof)
- Mortgage: Loan modification denial, foreclosure notices, payment history
For employment claims, your termination notice is the key document. If you never received one, that absence itself supports your case.
Mortgage claimants should gather all correspondence with their servicer. Denial letters and foreclosure filings are the strongest evidence.
Key Takeaway: Gather your financial records, receipts, and employer or servicer correspondence before starting your recession lawsuit claim form.
Recession Lawsuit News and Latest Updates
Recession lawsuit news today centers on the banking settlement approval hearing. A federal judge is expected to rule on final approval in June 2026.
The price gouging mediation sessions resumed in April 2026. Both sides have reportedly narrowed their differences on the total settlement fund.
New employment claims continue to pour in. The Department of Labor recently referred an additional 400,000 WARN Act complaints to the litigation team.
| Date | Development |
|---|---|
| January 2026 | Banking settlement preliminary approval granted |
| March 2026 | Banking claim filing portal opened |
| April 2026 | Price gouging mediation resumed |
| May 2026 | Employment discovery disputes resolved |
| June 2026 | Banking final approval hearing scheduled |
The mortgage track saw a major development in May 2026. Three additional servicers agreed to join the settlement negotiations.
Stay updated by checking the official settlement website regularly. Email alerts are available for all four claim categories.
Key Takeaway: The latest recession lawsuit news shows the banking track nearing final approval while other tracks advance through mediation and discovery.
Frequently Asked Questions
What is the surprising recession lawsuit about?
The surprising recession lawsuit is a series of class actions against banks, retailers, employers, and mortgage servicers. These companies allegedly exploited consumers during the 2024 to 2025 economic downturn. Over 14 million Americans may be eligible for compensation.
How much money can I get from the recession lawsuit?
Payouts range from $25 for minor retail claims to $25,000 for severe mortgage cases. Banking claimants average around $340 while employment claims average $5,500. Your exact amount depends on your documented losses.
What is the deadline to file a recession lawsuit claim?
The earliest deadline is July 31, 2026 for banking claims. Price gouging claims are due by October 15, 2026. Employment and mortgage deadlines extend into early 2027.
Do I need a lawyer to join the recession lawsuit?
No, you do not need a lawyer to file a claim. The settlement administrator provides a free online portal for all four claim categories. You can complete the entire process yourself in about 30 minutes.
When will recession lawsuit settlement payments start?
Banking track payments could begin as early as August 2026. Price gouging payments are projected for early 2027. Employment and mortgage payments will likely arrive in mid to late 2027.
Check your eligibility across all four tracks before the deadlines pass. Gather your documents now and file your claim through the official portal. The banking deadline of July 31, 2026 is approaching fast, so do not delay.







